About Stonehan Accountancy
At Stonehan Accountancy, P.C. (Stonehan), we bring unmatched expertise in financial and business management tailored specifically for the real estate sector. We transcend the role of traditional CPAs, offering a sophisticated, CFO-level approach to your financial needs. In today's complex and rapidly evolving market, we offer sophisticated investors the financial guidance and assurance needed to meticulously manage their real estate investments.
WHY CHOOSE STONEHAN?
Unparalleled Depth of Analysis:
Our commitment to rigorous scrutiny and contrarian thinking ensures we delve deeper than most to vet investment opportunities and partners. This meticulous approach allows us to confidently identify lucrative ventures that meet your high standards.
CFO-Led Expertise:
With a leadership background that includes managing a $1B Real Estate Lending Fund registered with the SEC and serving over 1,400 investors, our CFO brings unparalleled financial acumen and strategic insight to your portfolio.

Comprehensive Asset Management:
We manage assets exceeding $25 million, showcasing our capability to handle substantial portfolios with precision and sophistication. Our experience ensures that every aspect of your investments is optimized for maximum return and minimal risk.
Innovative Real Estate Development:
As Co-GP/CFO of a Modular Real Estate Development project, we integrate financial expertise with hands-on development experience, providing a unique perspective that enhances your real estate investments.
Entrepreneurial Perspective:
Having started our own CPA practice, we infuse every client engagement with entrepreneurial energy and innovative thinking. This dynamic approach allows us to deliver exceptional service and proactive financial solutions.
Entrust Stonehan with your real estate financial needs and experience the benefits of working with a firm dedicated to optimal planning, implementation, management, and control of your real estate financial operations. Discover how Stonehan Accountancy, P.C. can transform the financial elements of your real estate business with precision and sophistication.
From the Vault
How is real estate income actually taxed for investors and fund managers?
Real estate income is taxed according to three things: the character of the income, the entity it flows through, and your level of participation. Get all three right and depreciation can shelter income from outside the real estate itself. Get any one wrong and deductions suspend. This guide walks the full chain, from what kind of income you have to what actually lands on your return.
Part 1 — You are in two businesses at once
Before any of the mechanics, a framing point that shapes everything that follows.
If you raise capital and buy real estate, you are running two businesses simultaneously, and they have different customers.
The asset business. Your customers are tenants. You collect rent, manage operations, control expenses, and create value in the property.
The capital business. Your customers are investors. You raise money, report to LPs, deliver K-1s on time, and produce after-tax returns they can actually use.
The tax code treats these differently, and so should your structure. Income from the asset business is ownership income, carrying the character of the underlying property. Income from the capital business is service income, earned and subject to self-employment tax. Nearly every structuring mistake we correct comes from collapsing the two into one entity.
Part 2 — What kind of income is it?
Character determines rate. It is the first question in any real estate tax analysis.
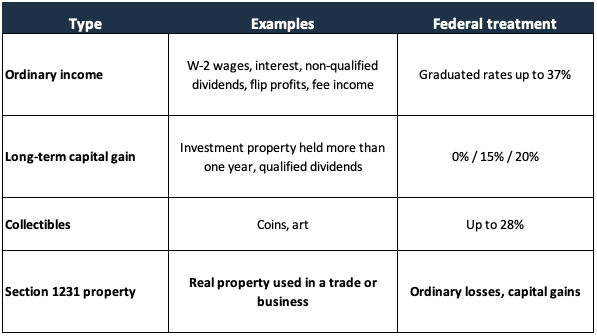
That last row is the one that makes real estate structurally advantaged, and it deserves emphasis. Under §1231, property used in a trade or business gets the best of both worlds: losses are treated as ordinary and can offset ordinary income, while net gains are treated as long-term capital gain at preferential rates. Most asset classes make you choose. Real estate does not.
Layered on top are transaction taxes (sales, transfer, property), state and sometimes city income taxes, cross-border regimes for foreign investors under FIRPTA, and estate and gift taxes at the end. Federal income tax is one line in a longer bill.
Are you a dealer or an investor?
This distinction decides whether §1231 is available to you at all.
The IRS views a homebuilder the way it views a widget factory. You build inventory, you sell inventory, you have ordinary income — plus self-employment tax. That is dealer status, and certain strategies fall into it naturally. Fix-and-flip is the common one.
Investor status produces capital gain treatment. The distinction turns on intent, which is evidenced by conduct: how long you held, whether you rented it, how many similar transactions you do, and how you marketed it. The widely used rule of thumb is holding for more than a year while genuinely renting for investment purposes — but no single fact controls, and the IRS looks at the pattern.
The same person can be a dealer as to some properties and an investor as to others, which is an argument for keeping the two activities in separate entities with separate records.
Part 3 — Which entity should hold it?
Entity choice determines what flows through to you and what gets blocked at the entity wall.
C corporations. Income is taxed at the corporate level, then again as dividends to shareholders. This double tax is why C corps are rare in real estate. They do appear in specific roles — as a management company in certain fact patterns, or as a blocker to shield tax-exempt investors from UBTI.
Partnerships and LLCs. The workhorse of real estate, and the reason is simple: pure flow-through. Income character flows through. Losses flow through. Critically, your share of entity debt flows through and increases your basis under §752, which is what allows a leveraged deal to generate a deduction larger than your cash investment.
A useful mental model, and one that makes the partnership rules far more intuitive: the IRS essentially treats a partnership as a group of sole proprietors operating together. There is no corporate layer in between, so almost nothing gets blocked.
Note that “partnership” is a tax classification, not a legal form. The legal entity can be an LLC, a limited partnership, or an LLP.
S corporations. Excellent for operating businesses, because a reasonable salary is subject to payroll tax and the remaining distributions are not. This is the right home for fee income once a management company nets roughly $60,000–$80,000 a year, depending on your state.
But an S corp is a blocker. Under §1366(d), shareholder basis is stock basis plus direct shareholder loans — corporate-level debt creates none. Put an ownership interest in a leveraged real estate deal inside an S corp and the debt basis that would have made your depreciation usable never reaches you.
Use an S corp for fees. Never for ownership interests. This is the single most valuable structural rule in this guide.
REITs. A C corporation that elects REIT status and avoids entity-level tax by distributing at least 90% of taxable income. Used privately as a blocker for tax-exempt and pension investors, but compliance-heavy — a 100-shareholder minimum, asset and income tests, and severe consequences for failing any of them.
Tax-exempt investors. IRAs, 401(k)s and pension funds are a large share of LP capital, and they bring UBTI and UDFI considerations that must be handled at the fund level.
Disregarded entities. A single-member LLC is invisible for federal tax purposes — no separate return, activity reported on the owner’s return. Many revocable living trusts are similarly disregarded.
Part 4 — How much do you participate?
Here is where most of the money is won or lost, and where the vocabulary is most misleading.
“Passive” under §469 does not mean what it means in conversation. Your dividends and interest are not passive income — they are portfolio income. Passive means income or loss from a trade or business in which you do not materially participate, plus, by default, essentially all rental activity.
There are four positions:
Passive
You are an LP in a syndication with no involvement. Passive losses offset passive income and nothing else; the excess carries forward under §469(b) until you have passive income or dispose of the activity.
This is an under-rated position. An investor with substantial passive income can absorb a great deal of K-1 depreciation without logging a single hour. Our standing advice is to be deliberately one thing or the other — build a coherent passive portfolio, or commit to active — rather than drifting between them and stranding losses on both sides.
Active participation
A narrow allowance under §469(i): own at least 10%, participate in management decisions, and deduct up to $25,000 of rental loss against non-passive income. It phases out between $100,000 and $150,000 of modified AGI, which puts it out of reach for most people reading this.
Material participation
Seven tests under Treas. Reg. §1.469-5T(a). The two that matter in practice:
More than 500 hours in the activity during the year.
More than 100 hours, and no other individual works more. This is the test behind the short-term rental strategy.
Real estate professional status
The gateway for anyone wanting apartment or commercial depreciation against non-passive income. Under §469(c)(7), rental activity is per se passive no matter how many hours you work — unless you qualify.
Two conditions, both required, and both measured for one spouse individually:
More than half of all personal services you perform in any trade or business must be in real property trades or businesses, and
More than 750 hours in those real property trades or businesses.
Section §469(c)(7)(C) lists eleven qualifying activities: development, redevelopment, construction, reconstruction, acquisition, conversion, rental, operation, management, leasing and brokerage. Real estate finance, lending and capital raising are not on the list — a fact that surprises most syndicators.
REPS by itself deducts nothing. It removes the per-se-passive presumption; you then still have to materially participate in the rental activity. And for that second test, both spouses’ hours count under §469(h)(5).
Multiple properties are tested separately unless you make the grouping election under Treas. Reg. §1.469-9(g) to treat all rental real estate as a single activity — which is what makes the 500-hour threshold achievable for a real portfolio.
The short-term rental exception
If a property’s average period of customer use is seven days or less, it is not a rental activity under Treas. Reg. §1.469-1T(e)(3)(ii)(A). The per-se-passive rule never applies, and no REPS is required — only material participation, usually via the 100-hour test.
This is the most accessible route for a two-career household, and it is why the “short-term rental loophole” gets so much attention. It is not a loophole so much as a definitional boundary that has been in the regulations since 1988.
Part 5 — The four gates
Participation is only one of four tests. Every allocated loss must clear all of them, in order.
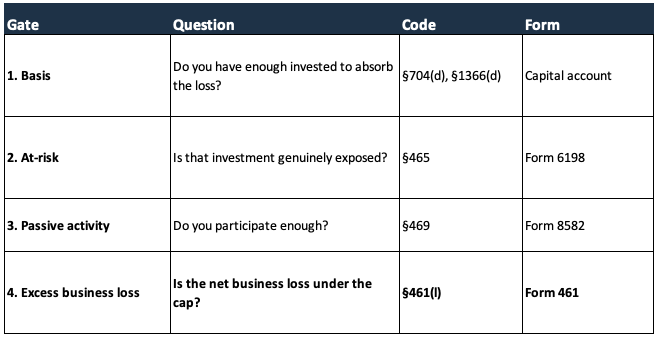
Gate four catches people who have done everything else right. Section §461(l) nets all your trades and businesses together — Schedule C, K-1s, qualifying rentals, §1231 gains — and caps the net loss that can shelter non-business income at $512,000 for joint filers in 2026 ($256,000 otherwise), per IRS Rev. Proc. 2025-32. That threshold fell from $626,000, and OBBBA made the limitation permanent.
Part 6 — Depreciation, the engine underneath
Everything above is plumbing. Depreciation is the water.
Real estate generates a deduction that is not a cash expense. You collect rent, and you deduct a portion of the building’s cost against it — so the cash flow arrives sheltered. A cost segregation study makes that deduction larger by reclassifying components into 5-, 7- and 15-year lives, all eligible for 100% bonus depreciation under §168(k) for property acquired after January 19, 2025.
Two things to hold together: REPS and the short-term rental exception make depreciation usable. Cost segregation and bonus depreciation make it big. You need both halves. A large deduction that suspends at a gate is not a tax benefit; it is a deferred one.
Part 7 — The 20% pass-through deduction
Section §199A allows a deduction of up to 20% of qualified business income from pass-through entities — partnerships, S corporations, sole proprietorships. OBBBA made it permanent.
It came about for parity. When TCJA cut the corporate rate, pass-through owners argued they were being left behind, and §199A was the answer. For clients who own everything through pass-throughs — which describes nearly everyone in real estate — it is one of the largest single deductions on the return.
It also phases out above certain income thresholds, more aggressively for a “specified service trade or business,” a category that captures many asset managers and advisory firms.
This is where deductions start stacking. An owner over the threshold gets no §199A benefit — but bring taxable income down with depreciation and other strategies, and the deduction can come back onto the table. Deductions that unlock other deductions are the most valuable kind, and modeling that interaction is most of what proactive planning is.
Part 8 — Deferral, and the exit that makes it permanent
Most of what real estate offers is deferral rather than elimination. That is not a criticism; deferral compounded over decades is close to elimination in economic terms. But it matters that you know which one you have.
§1031 exchanges defer gain when you roll investment property into like-kind replacement property — 45 days to identify, 180 days to close, and a qualified intermediary throughout. Note that a fund interest is a partnership interest, not real property, so you cannot 1031 into a syndication.
Refinancing takes cash out without a sale. Generally not taxable, though “generally” is doing real work in that sentence — distributions in excess of basis can be taxable, and whether the debt is recourse or qualified non-recourse determines who gets basis for it.
Opportunity Zones are one of the few places the code eliminates rather than defers. Made permanent by OBBBA, with new rules beginning in 2027.
The step-up at death. Under §1014, heirs take a basis equal to fair market value, and depreciation recapture is eliminated entirely. This is the exit that turns a lifetime of deferral into permanent savings, and it is why estate planning belongs in the same conversation as depreciation rather than a separate one years later.
The full pattern — buy, depreciate, refinance tax-free, exchange, repeat, step up at death — is the closest thing to tax-free wealth accumulation the code permits. Every step of it depends on the structural choices made at the beginning.
Where to go from here
If you take three things from this guide:
Character, entity and participation are one system, not three decisions. Changing any one of them changes what the other two produce.
Use an S corporation for fees and never for ownership. It is the most common expensive mistake in this industry, and it is invisible until the year you need the deduction.
Deductions have to be planned inside the tax year. By the time a return is being prepared, the year is closed. Everything described here is a forward-looking exercise.
Frequently asked questions
How is rental income taxed?
Rental income is ordinary income, but it is reduced by depreciation — a non-cash deduction that often shelters the cash flow entirely. On sale, real property used in a trade or business is Section 1231 property: net gains get long-term capital gain rates while losses are treated as ordinary.
What is the difference between passive and active real estate income?
Passive income comes from a trade or business in which you do not materially participate, and rental activity is passive by default. Active or non-passive income comes from activities where you materially participate. Passive losses can only offset passive income, which is why participation level determines whether depreciation is usable.
What entity should hold my real estate?
Almost always a partnership or LLC, because entity debt flows through and increases your basis under Section 752, making leveraged depreciation usable. S corporations are appropriate for fee and management income but block debt basis, so they should not hold ownership interests.
Can real estate losses offset W-2 income?
Yes, but only after clearing four limits: basis, at-risk, passive activity, and the Section 461(l) excess business loss cap of $512,000 for joint filers in 2026. Clearing the passive activity limit generally requires real estate professional status or the short-term rental exception.
What is Section 1231 property?
Real or depreciable property used in a trade or business and held more than one year. It receives favorable dual treatment: net gains are taxed as long-term capital gain while net losses are treated as ordinary and can offset ordinary income.
Do I pay self-employment tax on rental income?
Generally no. Rental income reported on Schedule E is not subject to self-employment tax. Fee income for services, flip profits and some short-term rental arrangements involving substantial services can be, which is a common reporting error we see on returns.
A second opinion on your structure
Most of what is described here was decided years ago, in a hurry, by someone who was thinking about the deal rather than the decade. That is normal. It is also why a structural review is usually the highest-return hour a real estate investor spends.
Stonehan offers a free 15-minute review. Send your last personal and business return, or bring your org chart. James will tell you what he would change and what it is worth.
Book a free 15-minute review →
James Bohan, CPA · Founder, Stonehan Accountancy, P.C. · Coeur d’Alene, Idaho CPA since 2011 · MRED, University of Southern California · Fourth-generation real estate developer · Former CFO of a private equity debt fund with $1B+ in originations
This article is educational content and is not tax advice. Tax advice requires a review of your specific facts and circumstances by a qualified professional. Provisions cited are current as of publication.
Our Core Values
Ruthless Skepticism
Meticulous Financial Planning
Comprehensive Vision
Contrarian Thinking
White-Glove Service
Ruthless Skepticism
Ruthless
Skepticism
Meticulous
Financial
Reporting
Comprehensive
Vision
Contrarian
Thinking
White-Glove
Service
Entrepreneurial
Execution
Big 4 Discipline.
Entrepreneurial Drive.
Click here to learn more about what it means to work at Stonehan, see the roles we have available, and submit your application to join our team.
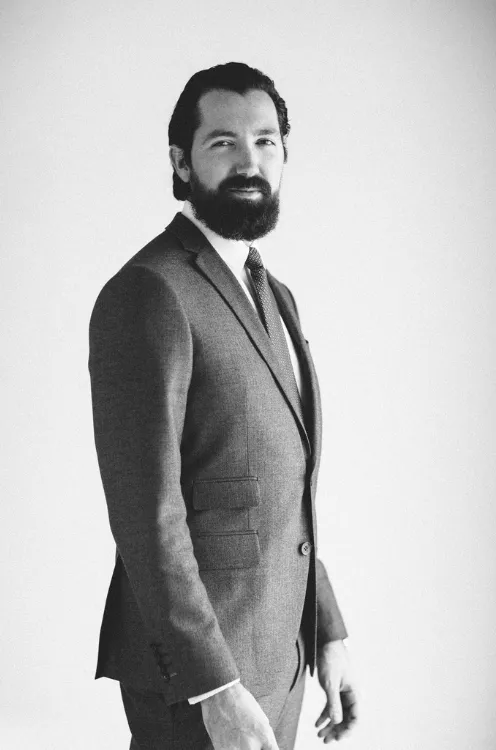
JAMES BOHAN – FOUNDER
James Bohan is a multi-faceted real estate professional, CPA, and entrepreneur. As the founder of Stonehan, he manages over $20MM of real estate while also providing accounting, tax, and fractional CFO solutions to real estate businesses, funds & syndicators . With more than 15 years’ of experience, he brings a wealth of knowledge in analyzing real estate transactions, tax structuring, creative financing techniques, and working capital management. Within the real estate investment management industry, Mr. Bohan is well regarded for his deep understanding of the complexities involved with a multitude of investment assets and complicated organizational structures.
Prior to Stonehan, James served as the inaugural employee and Chief Financial Officer of a Los Angeles-based real estate investment management firm, Mosaic Real Estate Investors. There, he played a key role in the firm’s growth and aligned the team through collaboration of management and stakeholders regarding strategic and financial planning, underwriting of debt and preferred equity investments, investor relations and reporting, risk management, compliance, cash flow, treasury, operating plans, tax matters, accounting, staffing, and policy development. Through his tenure with the company he oversaw all financial matters for the firm’s first ~$1B in loan commitments and the investor base grow to over 1,400 HNW investors and institutions.
Before joining Mosaic, James began his accounting career with the prestigious firm, Rothstein Kass, which was considered the premier boutique accounting firm for alternative investment vehicles: hedge fund, private equity, and venture capital firms. He worked there from 2010 until 2015 and during this time Rothstein was acquired by KPMG. James became an expert in real estate tax matters while offering tax and wealth management counsel to partnerships, trusts, REITs, corporations, and high-net-worth clients. He serviced private equity real estate firms with collective assets under management over $10B and consulted on over $2B of real estate transactions.
During this time from 2010 – 2015, James earned his California CPA license and was admitted to the Dollinger Master of Real Estate Development program at USC’s Sol Price School of Public Policy. He earned his Master’s in Real Estate Development (MRED) in 2015, graduating in the top 5% of his class and achieving an honorable mention for outstanding performance on the final comprehensive examination, all while continuing to work part-time for KPMG. He focused his undergraduate studies in Real Estate Finance and International Business, earning bachelor’s degrees in both Accounting and Business Administration from USC. His undergraduate academic achievements at USC included being accepted into the Marshall School of Business Honors Program and earning a spot on the Dean’s List. His collegiate social life centered around the Delta Chi Fraternity where he was elected to become a member of the executive committee. His summers were spent learning the nuances of real estate while serving internships in a variety of settings: residential mortgage lending, home building, and both corporate and onsite property management.
Mr. Bohan stays active professionally with involvement in the NIBCA, Information Management Network, and various other trade organizations. An avid traveler, he has visited over 40 countries, spent a semester studying abroad at Thammasat University in Thailand, and possesses dual citizenship in the United States of America and the Republic of Ireland.


⚡ Site Powered by BAMF Technology ⚡