About Stonehan Accountancy
At Stonehan Accountancy, P.C. (Stonehan), we bring unmatched expertise in financial and business management tailored specifically for the real estate sector. We transcend the role of traditional CPAs, offering a sophisticated, CFO-level approach to your financial needs. In today's complex and rapidly evolving market, we offer sophisticated investors the financial guidance and assurance needed to meticulously manage their real estate investments.
WHY CHOOSE STONEHAN?
Unparalleled Depth of Analysis:
Our commitment to rigorous scrutiny and contrarian thinking ensures we delve deeper than most to vet investment opportunities and partners. This meticulous approach allows us to confidently identify lucrative ventures that meet your high standards.
CFO-Led Expertise:
With a leadership background that includes managing a $1B Real Estate Lending Fund registered with the SEC and serving over 1,400 investors, our CFO brings unparalleled financial acumen and strategic insight to your portfolio.

Comprehensive Asset Management:
We manage assets exceeding $25 million, showcasing our capability to handle substantial portfolios with precision and sophistication. Our experience ensures that every aspect of your investments is optimized for maximum return and minimal risk.
Innovative Real Estate Development:
As Co-GP/CFO of a Modular Real Estate Development project, we integrate financial expertise with hands-on development experience, providing a unique perspective that enhances your real estate investments.
Entrepreneurial Perspective:
Having started our own CPA practice, we infuse every client engagement with entrepreneurial energy and innovative thinking. This dynamic approach allows us to deliver exceptional service and proactive financial solutions.
Entrust Stonehan with your real estate financial needs and experience the benefits of working with a firm dedicated to optimal planning, implementation, management, and control of your real estate financial operations. Discover how Stonehan Accountancy, P.C. can transform the financial elements of your real estate business with precision and sophistication.
From the Vault
Do I qualify for real estate professional status if my spouse works and I don’t?
Yes — and for most high-earning households, that is the only version that works. The 750-hour real estate professional test under §469(c)(7) must be satisfied by one spouse individually; hours cannot be combined to reach it. But once one spouse qualifies, both spouses’ hours count toward the separate material participation test on your properties. Two different tests, two different rules.
Why the high earner usually can’t be the real estate professional
Here is the structural problem, and it is the reason this strategy exists in the form it does.
To be a real estate professional you must satisfy two conditions in the same year:
More than half of all the personal services you perform in any trade or business must be in real property trades or businesses, and
You must perform more than 750 hours of service in those real property trades or businesses.
Read condition one again. It is a ratio, not a count. Someone working 2,000 hours a year as a physician, an attorney, a software executive — or a CPA — would need more than 2,000 hours in real estate to clear it. That is a second full-time job, and the Tax Court is not sympathetic to claims that it happened quietly on evenings and weekends.
I am in this position myself. I run an accounting practice at 1,500 to 2,000 hours a year and spend maybe 500 hours on our rental portfolio. I cannot qualify. My wife can, and does.
That is not a workaround. It is how the provision is designed to operate for a married couple, and it is why the highest-value version of this strategy usually involves a spouse whose primary occupation is the real estate.
Can spouses combine hours to reach 750?
No. This is the single most common error, and it is expensive to get wrong.
Section §469(c)(7)(B) says the qualification is determined separately for each spouse, even on a joint return. If you log 400 hours and your spouse logs 400 hours, neither of you is a real estate professional. One of you needs more than 750, and that same person needs those hours to represent more than half of their total working time.
The one narrow allowance: for the first test — the more-than-half-of-personal-services prong — a spouse’s hours are still counted only for that spouse. There is no pooling.
Then whose hours count for material participation?
Both. And this is where the strategy actually gets made.
Qualifying as a real estate professional does not deduct anything. All it does is remove the §469 rule that treats rental activity as automatically passive no matter how hard you work. Once that presumption is gone, you face the ordinary material participation test — and here, §469(h)(5) says participation by a spouse counts as participation by the taxpayer.
So the sequence is:
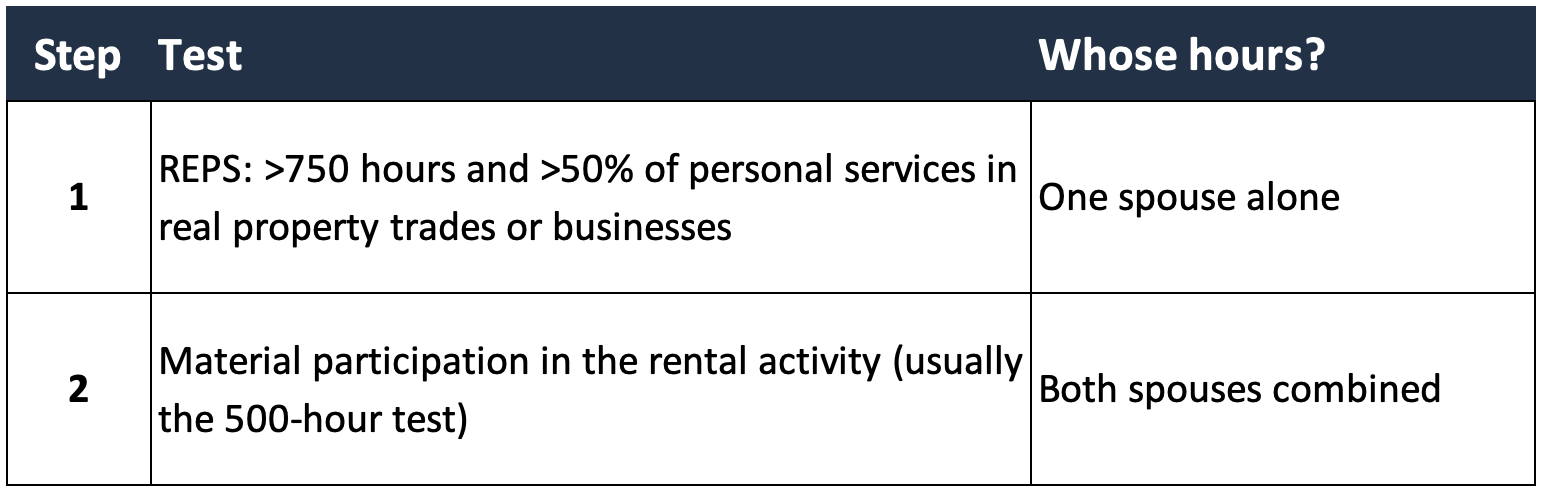
Worked example: Your spouse works 750 hours as a licensed agent showing homes, plus 250 hours managing your own rental portfolio — 1,000 hours total, all of it in real estate, comfortably more than half of their working time. Step one: cleared.
But agent hours showing other people’s houses do not count as participation in your properties. On their own, 250 hours falls short of the 500-hour material participation threshold.
Now add your 300 hours managing the same portfolio. Combined: 550 hours. Step two: cleared.
The result is that all of the portfolio’s depreciation becomes non-passive and available against your professional income — and it only works because the two tests use different rules about whose hours count.
What counts as a real property trade or business?
Section §469(c)(7)(C) gives an exhaustive list of eleven: development, redevelopment, construction, reconstruction, acquisition, conversion, rental, operation, management, leasing, and brokerage.
Notice what is not on it.
Real estate finance does not count. Mortgage brokerage, loan origination, and lending are not real property trades or businesses for this purpose. Neither is capital raising — which matters enormously for the syndicator audience. If your working week is spent talking to LPs and building models, those hours are not building toward REPS, however real-estate-adjacent they feel.
Two further conditions catch people:
Employee hours generally don’t count unless you own more than 5% of the employer. A property manager on someone else’s payroll with no equity cannot use those hours.
Personal services means your own labor. Capital committed, deals sourced by others, and work performed by contractors do not accrue to you.
Group your properties, or fail the 500-hour test
This is the technical step that most self-directed investors miss entirely.
By default, material participation is tested activity by activity. Own five rental properties and you must clear 500 hours on each one — essentially impossible for anyone with a diversified portfolio.
Treasury Regulation §1.469-9(g) lets a qualifying real estate professional elect to treat all interests in rental real estate as a single activity. Make the election, and you test 500 combined hours across the whole portfolio instead of property by property.
For our own five properties in Idaho, this is the difference between qualifying easily and not qualifying at all.
Three things to know about the election:
It is made by attaching a statement to your original return, and it is binding for all future years unless there is a material change in facts and circumstances.
It aggregates rentals for the material participation test — it does not change the REPS hour count itself.
If you missed it in a prior year, relief for a late election may be available under Rev. Proc. 2011-34. Worth asking about before assuming the year is lost.
Once the election is in place, LP interests in syndications can also be brought into the grouping in appropriate circumstances — which is how a portfolio of passive investments starts contributing to an active, deductible position.
What if neither spouse can get there?
REPS is not the only route, and it is not always the right one.
The short-term rental exception. If a property’s average period of customer use is seven days or less, it is not a “rental activity” under Treas. Reg. §1.469-1T(e)(3)(ii)(A) at all — so the per-se-passive rule never applies and REPS is not required. You need only material participation, most often through the test requiring more than 100 hours where no other individual works more. This is the single best option for a two-career household.
Build passive income instead. An investor with substantial passive income can absorb passive losses without any hours at all. This is a legitimate strategic position, not a consolation prize. Our general advice is to be deliberately one thing or the other rather than drifting: build a coherent passive portfolio, or commit to active status.
Time the transition. For clients moving from one posture to the other, the sequencing matters. A year in which accumulated passive losses have been cleared is usually the right year to shift into active status, so nothing gets trapped on the wrong side of the line.
The part people underestimate
Real estate professional status is one of the highest-value positions in the individual tax code, and the IRS knows it. Hours are the entire case, and hours are what get examined.
The regulation itself is more permissive than its reputation — Treas. Reg. §1.469-5T(f)(4) allows participation to be established by any reasonable means and does not strictly require daily time reports. But the Tax Court has repeatedly rejected after-the-fact reconstructions, and taxpayers who show up with a spreadsheet built the week before the exam tend to lose, sometimes with accuracy-related penalties on top.
If your hours are comfortably over the line, documentation is a formality. If they are close, it is the whole case. Build the log as you go.
Frequently asked questions
Can my spouse and I combine hours to reach 750 for real estate professional status?
No. Section §469(c)(7)(B) requires the 750-hour test and the more-than-half-of-personal-services test to be met by one spouse individually, even on a joint return. Hours cannot be pooled to reach the threshold.
Do both spouses’ hours count for material participation?
Yes. Once one spouse qualifies as a real estate professional, §469(h)(5) treats participation by either spouse as participation by the taxpayer, so both spouses’ hours count toward the 500-hour material participation test on your properties.
Can I qualify for REPS if I have a full-time job?
It is very difficult. More than half of all your personal services must be in real property trades or businesses, so a 2,000-hour job would require more than 2,000 hours in real estate. For most two-income households, one spouse qualifies or the short-term rental exception is used instead.
Does capital raising count toward real estate professional hours?
No. The eleven qualifying real property trades or businesses in §469(c)(7)(C) do not include real estate finance, lending, mortgage brokerage or capital raising. Syndicators are often surprised that their core activity does not build toward REPS.
Do I need to make a grouping election?
Almost certainly, if you own more than one rental property. Without the election under Treas. Reg. §1.469-9(g), material participation is tested separately on each property, requiring 500 hours per property rather than 500 hours across the portfolio.
Is being a licensed realtor enough to qualify?
No. A license is evidence of the type of work but proves nothing about hours. You still need to document more than 750 hours and more than half your personal service time, and then separately establish material participation in your own rental activities.
Is your return actually claiming what you think it is?
We regularly review returns where a client believes they are treated as a real estate professional and the return says otherwise — no grouping election attached, rentals still reported as passive, depreciation parked on Form 8582.
It takes about thirty seconds to check.
Stonehan offers a free 15-minute tax return review. Send your most recent return, and James will confirm whether your REPS position is actually reflected in the filing — and what it would take to fix it if not.
Book a free 15-minute review →
James Bohan, CPA · Founder, Stonehan Accountancy, P.C. · Coeur d’Alene, Idaho CPA since 2011 · MRED, University of Southern California · Fourth-generation real estate developer
This article is educational content and is not tax advice. Tax advice requires a review of your specific facts and circumstances by a qualified professional.
Our Core Values
Ruthless Skepticism
Meticulous Financial Planning
Comprehensive Vision
Contrarian Thinking
White-Glove Service
Ruthless Skepticism
Ruthless
Skepticism
Meticulous
Financial
Reporting
Comprehensive
Vision
Contrarian
Thinking
White-Glove
Service
Entrepreneurial
Execution
Big 4 Discipline.
Entrepreneurial Drive.
Click here to learn more about what it means to work at Stonehan, see the roles we have available, and submit your application to join our team.
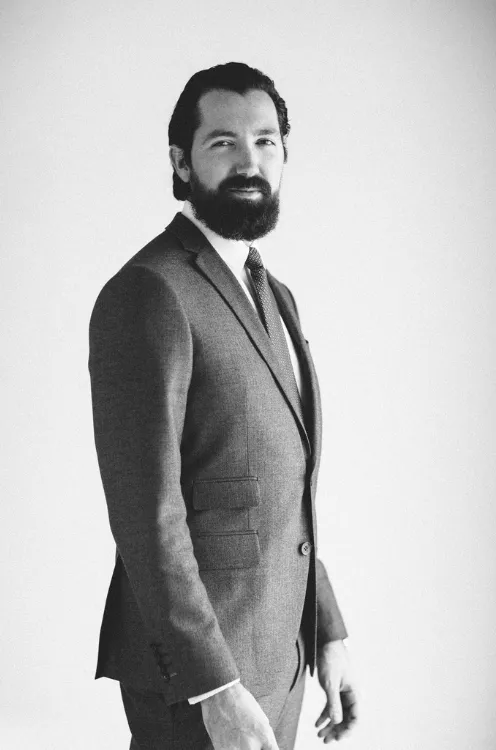
JAMES BOHAN – FOUNDER
James Bohan is a multi-faceted real estate professional, CPA, and entrepreneur. As the founder of Stonehan, he manages over $20MM of real estate while also providing accounting, tax, and fractional CFO solutions to real estate businesses, funds & syndicators . With more than 15 years’ of experience, he brings a wealth of knowledge in analyzing real estate transactions, tax structuring, creative financing techniques, and working capital management. Within the real estate investment management industry, Mr. Bohan is well regarded for his deep understanding of the complexities involved with a multitude of investment assets and complicated organizational structures.
Prior to Stonehan, James served as the inaugural employee and Chief Financial Officer of a Los Angeles-based real estate investment management firm, Mosaic Real Estate Investors. There, he played a key role in the firm’s growth and aligned the team through collaboration of management and stakeholders regarding strategic and financial planning, underwriting of debt and preferred equity investments, investor relations and reporting, risk management, compliance, cash flow, treasury, operating plans, tax matters, accounting, staffing, and policy development. Through his tenure with the company he oversaw all financial matters for the firm’s first ~$1B in loan commitments and the investor base grow to over 1,400 HNW investors and institutions.
Before joining Mosaic, James began his accounting career with the prestigious firm, Rothstein Kass, which was considered the premier boutique accounting firm for alternative investment vehicles: hedge fund, private equity, and venture capital firms. He worked there from 2010 until 2015 and during this time Rothstein was acquired by KPMG. James became an expert in real estate tax matters while offering tax and wealth management counsel to partnerships, trusts, REITs, corporations, and high-net-worth clients. He serviced private equity real estate firms with collective assets under management over $10B and consulted on over $2B of real estate transactions.
During this time from 2010 – 2015, James earned his California CPA license and was admitted to the Dollinger Master of Real Estate Development program at USC’s Sol Price School of Public Policy. He earned his Master’s in Real Estate Development (MRED) in 2015, graduating in the top 5% of his class and achieving an honorable mention for outstanding performance on the final comprehensive examination, all while continuing to work part-time for KPMG. He focused his undergraduate studies in Real Estate Finance and International Business, earning bachelor’s degrees in both Accounting and Business Administration from USC. His undergraduate academic achievements at USC included being accepted into the Marshall School of Business Honors Program and earning a spot on the Dean’s List. His collegiate social life centered around the Delta Chi Fraternity where he was elected to become a member of the executive committee. His summers were spent learning the nuances of real estate while serving internships in a variety of settings: residential mortgage lending, home building, and both corporate and onsite property management.
Mr. Bohan stays active professionally with involvement in the NIBCA, Information Management Network, and various other trade organizations. An avid traveler, he has visited over 40 countries, spent a semester studying abroad at Thammasat University in Thailand, and possesses dual citizenship in the United States of America and the Republic of Ireland.


⚡ Site Powered by BAMF Technology ⚡