About Stonehan Accountancy
At Stonehan Accountancy, P.C. (Stonehan), we bring unmatched expertise in financial and business management tailored specifically for the real estate sector. We transcend the role of traditional CPAs, offering a sophisticated, CFO-level approach to your financial needs. In today's complex and rapidly evolving market, we offer sophisticated investors the financial guidance and assurance needed to meticulously manage their real estate investments.
WHY CHOOSE STONEHAN?
Unparalleled Depth of Analysis:
Our commitment to rigorous scrutiny and contrarian thinking ensures we delve deeper than most to vet investment opportunities and partners. This meticulous approach allows us to confidently identify lucrative ventures that meet your high standards.
CFO-Led Expertise:
With a leadership background that includes managing a $1B Real Estate Lending Fund registered with the SEC and serving over 1,400 investors, our CFO brings unparalleled financial acumen and strategic insight to your portfolio.

Comprehensive Asset Management:
We manage assets exceeding $25 million, showcasing our capability to handle substantial portfolios with precision and sophistication. Our experience ensures that every aspect of your investments is optimized for maximum return and minimal risk.
Innovative Real Estate Development:
As Co-GP/CFO of a Modular Real Estate Development project, we integrate financial expertise with hands-on development experience, providing a unique perspective that enhances your real estate investments.
Entrepreneurial Perspective:
Having started our own CPA practice, we infuse every client engagement with entrepreneurial energy and innovative thinking. This dynamic approach allows us to deliver exceptional service and proactive financial solutions.
Entrust Stonehan with your real estate financial needs and experience the benefits of working with a firm dedicated to optimal planning, implementation, management, and control of your real estate financial operations. Discover how Stonehan Accountancy, P.C. can transform the financial elements of your real estate business with precision and sophistication.
From the Vault
Which states will my fund have to file in?
Probably more than you budgeted for. Owning property in a state creates a filing obligation there — that part is expected. What catches sponsors is that an investor’s state of residence can create one too, independent of where the property sits. Each additional state means another return, an apportionment computation, and a depreciation recalculation under that state’s rules.
Two sources of obligation, not one
Every fund manager plans for the first. Almost none plan for the second.
Where the property is. Buy an apartment building in Missouri and the fund will file in Missouri. Straightforward, foreseeable, and priced into the deal.
Where the investors are. Some states take the position that a pass-through entity with a resident partner has a connection to that state, whether or not the entity owns anything there. Admit one investor from such a state and you may have added a return to your annual compliance load — permanently, for the life of the fund.
The second category is what turns a clean two-state fund into a seven-state fund over the course of a raise. And it happens one subscription at a time, usually without anyone running the analysis, because the person accepting the wire is thinking about closing the round rather than about next April.
Rules differ by state and change frequently. Do not rely on a list you found in a blog post — including this one. Confirm the current position state by state before you accept capital from a new jurisdiction. Our worksheet at the end gives you the framework to do that.
The three regimes
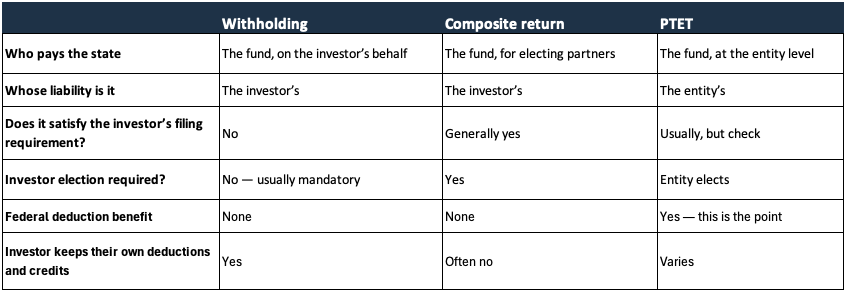
When a state does have a claim, there are three mechanisms it may use to collect. Knowing which applies determines what your investors have to do, and that is a question you will be asked on every capital call.
Withholding
The traditional mechanism. The fund withholds tax on the nonresident partner’s allocable share of state-source income and remits it.
The investor still has to file their own return in that state — they report the income, claim the withholding as a credit, and either pay a little more or get a refund. Withholding is a prepayment, not a substitute for filing.
Rates and thresholds vary widely, and several states allow a waiver or exemption if the partner files an agreement to pay the tax directly.
Composite returns
The fund files a single return on behalf of electing nonresident partners and pays the tax for them. For the electing partner, that generally satisfies the state filing requirement — one less return to prepare.
The convenience has a cost. Composite returns often apply the top marginal rate, may deny personal exemptions, deductions and credits, and typically cannot use losses from the investor’s other activities in that state.
Where composite goes wrong. Suppose an investor has income from your Missouri deal and a loss from a different sponsor’s Missouri deal. On a composite, they pay tax on your income with no ability to net the other loss. To recover it they have to file individually anyway — which is the outcome the composite was supposed to avoid.
The rule of thumb: composite works well for an investor whose only connection to that state is your fund. It works badly for anyone with other activity there. Which is why the election is per partner and per year, and why you should not push all your investors into it as a default.
PTET — the pass-through entity tax
The newest regime, and for most funds the most valuable.
PTET was designed as a workaround to the federal cap on state and local tax deductions. An individual’s SALT deduction is capped. A business deduction for state taxes is not. So states created an elective entity-level tax: the partnership pays the state tax, deducts it as a business expense at the federal level, and passes the partners a credit or an income exclusion.
The result is that state tax paid becomes federally deductible in substance, when it would otherwise have been trapped behind the individual cap. Over 35 states plus New York City have enacted one.
Two things sponsors should know about the current landscape.
OBBBA left PTET alone. There were proposals during the legislative process to restrict or eliminate the deduction, particularly for service businesses. None of them made it into the final bill. PTET deductibility, eligibility and the ability to elect are unchanged.
What did change is the cap itself. The SALT cap rose to $40,000 for 2025, with modest annual increases through 2029, and phases down for taxpayers with modified AGI above $500,000 — with a $10,000 floor. It reverts to $10,000 in 2030.
That combination matters for how you advise investors. For a high-income LP whose SALT deduction phases back down toward the floor, PTET is doing as much work as it ever did. For an investor comfortably under the new cap, the calculus is different. And since the expansion is temporary, a fund with a seven-year life will operate under both regimes.
Mechanics vary more than people expect. Election deadlines, whether the election binds for multiple years, estimated payment requirements, whether the benefit flows to partners as a credit or an exclusion, and whether nonresidents are covered — all differ by state. A missed election deadline is not curable, and it costs real money.
And the credit does not always come home. An investor’s resident state may or may not give full credit for PTET paid to another state on their behalf. That is an investor-level question, but you will be asked it.
What this costs your fund, and who pays
Every additional state is real money: a return, apportionment, a state-specific depreciation computation under conventions that may not match federal, estimated payments, and registration and annual report fees.
Those costs are billed to the fund. Which means they are borne by all the investors, including the ones who did not create them.
That is not an argument for turning away capital. When you are raising your first fund you take every dollar you can get, and you should. It is an argument for knowing the cost when you take it, so that:
You budget for it rather than discovering it.
You can make an informed decision about concentrating your raise in fewer states where you have the option.
You are not surprised by a fund expense line that your LPs will eventually ask about.
Some sponsors handle this well by simply being transparent — the offering explains that multistate compliance is a fund expense and roughly what it runs. Investors respect that far more than a surprise.
Fund-of-funds: push the reporting down
If you sit above other sponsors, you cannot produce accurate state K-1s without apportionment detail from every lower-tier fund. And those managers have no reason to track it if they have no investors who need it.
Get the obligation into the subscription documents and side letters at the outset. Chasing it three years later — from a manager who may have wound down the fund or left the business — is a bad position, and it is your investors who bear the consequence.
The same discipline applies to UBTI reporting for tax-exempt investors, and for the same reason.
Also worth knowing
Blockers block state tax too. A REIT blocker inserted to manage UBTI can also block state filing obligations from flowing through to investors. If you are already weighing a blocker for tax-exempt capital, the state benefit belongs in the same analysis.
Watch the disposition year. States generally require withholding or payment on gain from the sale of real property located there. A fund that has been quiet on state compliance for six years can face a substantial obligation in the exit year, and reserves need to account for it. Note also that Washington taxes capital gains even though it has no general income tax — the kind of detail that gets missed precisely because “Washington has no income tax” is nearly true.
Registration is separate from tax. Doing business in a state may require foreign qualification with the Secretary of State, with its own fees and annual reports, independent of any income tax filing.
You don’t need to become a state tax expert
You need to know two things: which states your fund touches, and that each one carries an obligation you have not yet priced.
That first question is the one only you can answer, and it is the one nobody asks until a return is late. It does not require research subscriptions or a tax library. It requires a list of where you own property and a list of where your investors live — both of which are sitting in your subscription documents right now.
Once you have that list, you have something specific to ask about: here are our nine states, what do we owe in each? That is a short, answerable engagement. Compare it to the alternative, which is discovering in year three that you have been non-filing in two jurisdictions and now owe tax, interest, penalties and amended K-1s for every affected investor.
The tracker below produces that list. What it deliberately does not do is tell you each state’s rules, because those change most years and a stale answer is worse than no answer.
The practical sequence
Before you accept a subscription from a new state, check whether that state asserts a filing obligation based on partner residency.
Model the cost of the additional state against the size of the commitment.
Decide the regime — withholding, composite, or PTET — before the first return, not at extension time.
Diarize the PTET election deadline for every state where you will elect. Missed deadlines are not fixable.
Ask each investor whether they have other activity in that state before defaulting them into a composite.
Re-verify annually. These rules move.
Frequently asked questions
Does my fund have to file in states where my investors live?
Sometimes. Some states assert a filing obligation based on partner residency alone, independent of where the property is located. Because the rules differ by state and change frequently, confirm the current position for each state before accepting capital from a new jurisdiction.
What is the difference between withholding and a composite return?
Withholding is a prepayment of the investor’s own liability — they still file their own return in that state and claim the credit. A composite return is filed by the fund for electing partners and generally satisfies their filing requirement, but often applies top marginal rates and denies personal deductions and credits.
What is a PTET election?
An elective entity-level state tax. The partnership pays the state tax and deducts it as a business expense federally, then passes partners a credit or income exclusion. It converts state tax that would be trapped behind the individual SALT cap into an effectively deductible business expense. Over 35 states plus New York City have one.
Did OBBBA eliminate the PTET workaround?
No. Proposals to restrict PTET deductibility were considered but did not make it into the final bill. OBBBA made no changes to PTET deductibility, who may elect, or the ability to elect. What changed is the SALT cap itself, which rose to $40,000 for 2025 with phase-downs above $500,000 of modified AGI, reverting to $10,000 in 2030.
Should all my investors join the composite return?
No. A composite suits an investor whose only connection to that state is your fund. An investor with other activity there — particularly losses — may be unable to net it on a composite and will have to file individually anyway. Ask before defaulting anyone into it.
Who pays for multistate compliance?
Ordinarily the fund, which means all investors share the cost, including those who did not create it. This is worth disclosing in the offering rather than leaving investors to discover it in the expense line.
How do I work out which states my fund is exposed to?
Start with two lists you already have: every state where the fund owns property, and every state where an investor resides — using the entity’s state for IRA, trust and LLC investors. The combined list is your footprint, and each state on it needs five questions answered before the next filing season.
Find out which states your fund actually touches
Fifteen minutes with your subscription list. Enter where you own property and where each investor resides, and the tracker returns every state in your footprint — separating the ones you expected from the ones your raise created — along with the five questions to get answered for each.
It also flags your retirement-account investors, which matter for two other reasons: UBTI reporting, and the ERISA 25% per-class threshold.
[Download the Fund State Footprint Tracker (.xlsx) →]
Then bring the list to someone who can answer it
Knowing you have nine states is the hard part. Getting the answers for nine specific states is a short, bounded piece of work — and far cheaper than discovering a non-filing position three years in, when it comes with interest, penalties and amended K-1s for every affected investor.
Stonehan handles fund returns, K-1 delivery and multistate compliance for sponsors who would rather this were somebody else’s calendar.
Book a free 15-minute consultation →
James Bohan, CPA · Founder, Stonehan Accountancy, P.C. · Coeur d’Alene, Idaho CPA since 2011 · MRED, University of Southern California · Former CFO, private equity debt fund
This article is educational content and is not tax advice. State pass-through rules, withholding rates, composite availability and PTET mechanics vary by state and change frequently. Confirm the current position for your specific states with a qualified professional before relying on any general description.
Our Core Values
Ruthless Skepticism
Meticulous Financial Planning
Comprehensive Vision
Contrarian Thinking
White-Glove Service
Ruthless Skepticism
Ruthless
Skepticism
Meticulous
Financial
Reporting
Comprehensive
Vision
Contrarian
Thinking
White-Glove
Service
Entrepreneurial
Execution
Big 4 Discipline.
Entrepreneurial Drive.
Click here to learn more about what it means to work at Stonehan, see the roles we have available, and submit your application to join our team.
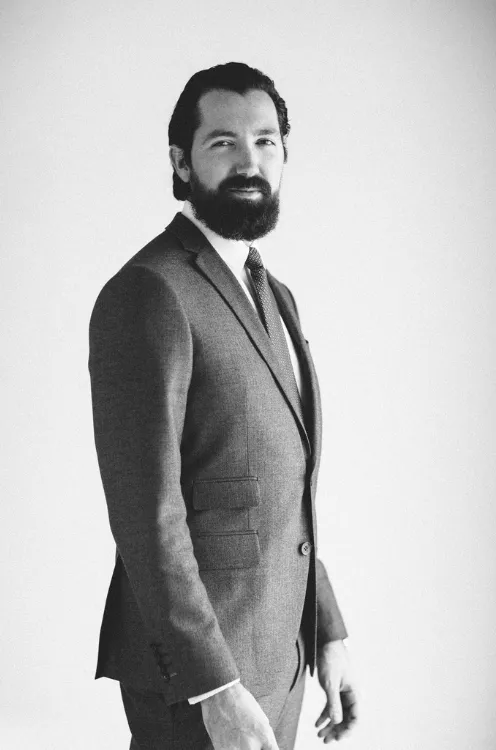
JAMES BOHAN – FOUNDER
James Bohan is a multi-faceted real estate professional, CPA, and entrepreneur. As the founder of Stonehan, he manages over $20MM of real estate while also providing accounting, tax, and fractional CFO solutions to real estate businesses, funds & syndicators . With more than 15 years’ of experience, he brings a wealth of knowledge in analyzing real estate transactions, tax structuring, creative financing techniques, and working capital management. Within the real estate investment management industry, Mr. Bohan is well regarded for his deep understanding of the complexities involved with a multitude of investment assets and complicated organizational structures.
Prior to Stonehan, James served as the inaugural employee and Chief Financial Officer of a Los Angeles-based real estate investment management firm, Mosaic Real Estate Investors. There, he played a key role in the firm’s growth and aligned the team through collaboration of management and stakeholders regarding strategic and financial planning, underwriting of debt and preferred equity investments, investor relations and reporting, risk management, compliance, cash flow, treasury, operating plans, tax matters, accounting, staffing, and policy development. Through his tenure with the company he oversaw all financial matters for the firm’s first ~$1B in loan commitments and the investor base grow to over 1,400 HNW investors and institutions.
Before joining Mosaic, James began his accounting career with the prestigious firm, Rothstein Kass, which was considered the premier boutique accounting firm for alternative investment vehicles: hedge fund, private equity, and venture capital firms. He worked there from 2010 until 2015 and during this time Rothstein was acquired by KPMG. James became an expert in real estate tax matters while offering tax and wealth management counsel to partnerships, trusts, REITs, corporations, and high-net-worth clients. He serviced private equity real estate firms with collective assets under management over $10B and consulted on over $2B of real estate transactions.
During this time from 2010 – 2015, James earned his California CPA license and was admitted to the Dollinger Master of Real Estate Development program at USC’s Sol Price School of Public Policy. He earned his Master’s in Real Estate Development (MRED) in 2015, graduating in the top 5% of his class and achieving an honorable mention for outstanding performance on the final comprehensive examination, all while continuing to work part-time for KPMG. He focused his undergraduate studies in Real Estate Finance and International Business, earning bachelor’s degrees in both Accounting and Business Administration from USC. His undergraduate academic achievements at USC included being accepted into the Marshall School of Business Honors Program and earning a spot on the Dean’s List. His collegiate social life centered around the Delta Chi Fraternity where he was elected to become a member of the executive committee. His summers were spent learning the nuances of real estate while serving internships in a variety of settings: residential mortgage lending, home building, and both corporate and onsite property management.
Mr. Bohan stays active professionally with involvement in the NIBCA, Information Management Network, and various other trade organizations. An avid traveler, he has visited over 40 countries, spent a semester studying abroad at Thammasat University in Thailand, and possesses dual citizenship in the United States of America and the Republic of Ireland.


⚡ Site Powered by BAMF Technology ⚡